 How-to
7 Steps to Vet Tenants Effectively
Last Updated: October 26, 2026
Quick Summary
To vet tenants effectively, define clear screening criteria in writing before listing your property, then consistently apply those criteria to verify identity, income, employment, credit history, and rental history for every applicant using a standardized checklist and scoring rubric.
- Set minimum income at three times monthly rent and require applicants to earn at least that amount to qualify.
- Use a standardized rental application form with the same questions for all applicants to ensure fair and consistent evaluation.
- Contact previous employers and landlords directly using independently verified contact information, not numbers the applicant provides.
- Pull a credit report only with written authorization and provide an adverse action notice if you deny based on it.
- Document every verification step, decision reason, and applicant score in a decision log to create a defensible record.
Table of Contents
- Define Your Tenant Screening Criteria Before You List
- Create a Rental Listing That Communicates Your Requirements
- Pre-Screen Applicants and Collect Complete Rental Applications
- Verify Identity and Review Application Details for Consistency
- How to Verify Tenant Income and Employment
- Review Credit History and Assess Ability to Pay Rent
- Conduct Rental History Checks and Ask Landlord Reference Questions
- Use a Tenant Screening Checklist and Document Your Decision
- Frequently Asked Questions
Define Your Tenant Screening Criteria Before You List
Before you show your property, know exactly who you're looking for. Clear tenant screening criteria help you vet tenants effectively, protect your investment, and keep the process fair and consistent.
Define minimum income, credit score, employment history, and rental history requirements in writing so every applicant is evaluated the same way.
Keep criteria consistent, objective, and applied equally to all applicants. Written standards protect you legally, speed up decisions, reduce disputes, and demonstrate fair housing compliance.
Consider working with professionals who understand local rental laws. Full-Service Property Management in San Bernardino County shows how professional property management handles tenant vetting as part of comprehensive offerings. How to Screen Rental Tenants Effectively explores this topic in depth and can help you refine your approach.
Create a Rental Listing That Communicates Your Requirements
Your rental listing is your first screening tool. Be specific about requirements, clarity attracts qualified applicants and discourages those who don't meet your standards.
State your minimum income clearly.
List your tenant screening criteria in the listing itself:
- Minimum credit score requirement
- Employment verification needed
- Rental references required
Be honest about what you're looking for. If you need a long-term tenant or require a co-signer for certain applicants, say so upfront.
How to Reduce Rental Property Vacancies: 7 Proven Steps addresses the next step after vetting: reducing vacancies through effective tenant selection and retention.
Pre-Screen Applicants and Collect Complete Rental Applications
Pre-screening happens before formal applications. When prospects call or email, ask basic questions: Do they have the income you require? Are they employed?
Use a standardized rental application form. Every applicant should complete the same form with the same questions. Your application should ask for:
- Full legal name and Social Security number
- Current and previous addresses
- Employment history and current employer contact information
Require proof of identity with the application. A driver's license or passport confirms identity matches the application and catches inconsistencies early.
Collect the application fee at submission. It covers screening costs and shows the applicant is serious, make clear it is non-refundable and what it covers.
Verify Identity and Review Application Details for Consistency
Review every detail for consistency. Cross-check addresses, employment history, and dates, and watch for gaps.
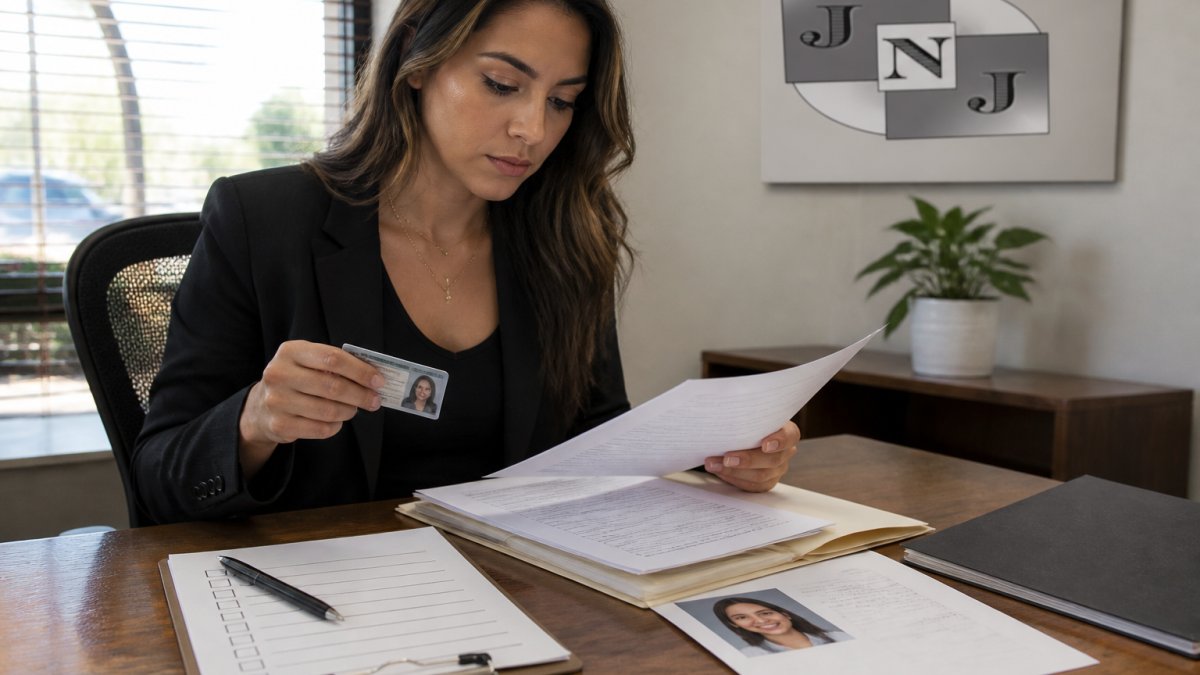
Verify the identity document matches the application, name, address, and date of birth should align. Learn about the pros and cons of professional property management to decide whether to hire professionals to handle tenant screening and vetting processes.
Call previous employers and landlords directly, looking up contact details independently rather than relying on numbers the applicant provides.
Document everything in writing, every call, verification, and inconsistency.
Watch for red flags like false employment dates, unexplained rental history gaps, or addresses that don't match previous records, these warrant deeper investigation.
How to Verify Tenant Income and Employment
Income verification confirms the applicant can afford rent. Request recent pay stubs (typically the last two months); for self-employed applicants, tax returns from the last two years.
Calculate the income-to-rent ratio. Most landlords want tenants spending no more than 30 percent of gross income on rent.
For applicants with irregular income or multiple jobs, ask for bank statements. They show actual deposits and reveal how much money the applicant actually has available.
Consider co-signers for lower-income applicants.
Review Credit History and Assess Ability to Pay Rent
A credit check reveals how applicants manage debt and whether they pay bills on time. Under the FCRA, you must have the applicant's written authorization before pulling a report, and you must provide an adverse action notice if you deny or modify the offer based on it (the FTC).
Look for patterns, not just numbers. A single late payment from years ago matters less than recent missed payments; recent defaults, collections, charge-offs, and judgments are serious red flags.
Understand the difference between a credit score and credit history.
Ask applicants to explain negative items. Job loss, medical emergencies, and divorce are valid explanations; others show a pattern of irresponsibility. Listen and verify what you can.
Set a minimum credit score and stick to it across all applicants.
Evaluating Applicants With Limited or Nontraditional Credit
A single score is a blunt instrument. Many reliable renters, recent graduates, immigrants, self-employed and gig workers, people rebuilding after a setback, have thin credit files.
Use these alternative indicators when the credit file is thin:
- 12 months of verified rent payments. Ask for canceled checks, bank statements showing recurring transfers to a landlord, or a landlord ledger. On-time rent is the single most relevant payment history you can obtain.
- Utility and phone payment history. Many utilities will provide a payment history letter on request. Consistent on-time payments demonstrate the same discipline a credit score is meant to capture.
- Bank statements showing stable deposits and a positive balance. Look for recurring income deposits, no overdrafts, and a cushion of at least one month's rent.
Apply the alternative framework consistently. Write it into your criteria alongside the credit minimum so every applicant is measured against the same standard, a common pattern is a two-path rubric: meet the credit threshold or satisfy a defined set of alternative indicators.
Resolving Errors and Disputes Before You Decide
Screening reports contain errors more often than most landlords assume, mismatched identities, records belonging to a relative with a similar name, outdated collections that were paid, or criminal records that were expunged. Before you deny an application based on a report, take these steps:
- Confirm identity match. Verify that the name, date of birth, and address on the report match the application. A common source of error is a junior/senior name collision or a former address shared with another person.
- Check dates and status. Confirm that collections, judgments, or criminal entries are current and belong to the applicant. Paid or dismissed items should not drive a denial.
- Give the applicant a chance to respond. Under the FCRA, if you take adverse action based in whole or in part on a consumer report, you must provide an adverse action notice identifying the reporting agency and informing the applicant of the right to dispute. Many landlords go further and share the specific reason before finalizing, which reduces disputes and demonstrates fairness.
- Document the resolution. Note what was disputed, what you verified, and how it affected the decision. This record is your defense if the decision is later challenged.
| Verification Step | What to Check | Red Flags to Watch |
|---|---|---|
| Identity | Driver's license or passport matches application | Mismatched names, addresses, or dates |
| Employment | Job title, dates, income verified with employer | Gaps in employment, temporary positions only |
| Income | Pay stubs, tax returns, bank statements | Income below 3x rent, irregular deposits |
| Credit | Payment history, score, recent delinquencies | Recent late payments, collections, judgments |
| Alternative credit | 12 months rent history, utility payments, bank statements | Overdrafts, no verifiable payment record |
| Rental History | Previous landlord references, payment record | Evictions, lease violations, property damage |
Conduct Rental History Checks and Ask Landlord Reference Questions
Rental history is one of your best predictors of future behavior. Contact previous landlords directly using contact information you find independently, not numbers the applicant provides. Ask specific questions:
- Did the tenant pay rent on time every month?
- Did they maintain the property in good condition?
- Were there any complaints from neighbors?
Listen for hesitation or vague answers. A landlord who won't recommend a tenant is sending a message.
Ask about lease violations or damage. Even minor damage matters, it shows whether the tenant respects property.
Request written references from previous landlords if possible.
Watch out for applicants with no rental history. First-time renters are riskier because you have no track record to check.
| Verification Step | What to Check | Red Flags to Watch |
|---|---|---|
| Identity | Driver's license or passport matches application | Mismatched names, addresses, or dates |
| Employment | Job title, dates, income verified with employer | Gaps in employment, temporary positions only |
| Income | Pay stubs, tax returns, bank statements | Income below 3x rent, irregular deposits |
| Credit | Payment history, score, recent delinquencies | Recent late payments, collections, judgments |
| Rental History | Previous landlord references, payment record | Evictions, lease violations, property damage |
Use a Tenant Screening Checklist and Document Your Decision
Create a standardized tenant screening checklist and use it for every applicant to vet tenants effectively. Include every verification step: identity check, income verification, employment verification, credit check, rental history verification, and any alternative-credit indicators you accept. Add space for notes and evidence on each item.
Build a Reusable Scoring Rubric
A checklist tells you what to collect; a rubric tells you how to weigh it. Build a simple point system and apply it identically to every applicant. A workable structure assigns points across four or five categories, for example:
- Income (0-30 points). Full points at or above three times the monthly rent; partial credit for documented co-signers or savings reserves.
- Credit (0-25 points). Tiered by score band, with an alternative-credit path for thin files that earns equivalent points when the indicators are strong.
- Rental history (0-25 points). Full points for verified on-time payments and a positive landlord reference; deductions for late payments, lease violations, or unexplained gaps.
Set a minimum total score in your written criteria and apply it to everyone. The rubric does two things a checklist cannot: it reduces subjective judgment, and it creates a defensible record that each applicant was measured against the same standard.
Document the Decision and the Reason
Document your final decision and the reasons for it. If you approve an applicant, write down why. If you deny an application, write down the specific reason tied to your written criteria, for example, "income below the 3x threshold" or "rental history showed two lease violations." Avoid subjective language.
Keep a decision log that records, for each applicant: the date the application was received, the criteria applied, the verification results, the score, the decision, and the date the decision was communicated. A single spreadsheet or secure folder is enough.
Follow the Adverse Action Workflow
If you deny an application or approve it on different terms based on a consumer report, the FCRA requires an adverse action notice. A practical workflow:
- Confirm the basis. Identify which report items drove the decision and verify they belong to the applicant.
- Send written notice. Provide the notice promptly, identify the consumer reporting agency used, state that the agency did not make the decision, and inform the applicant of the right to obtain a free copy of the report and to dispute its accuracy.
- Keep a copy. Retain the notice and the underlying report in the applicant's file.
- Respond to disputes. If the applicant disputes the report, document the dispute and re-verify before finalizing. Do not finalize a denial on a record you have reason to believe is inaccurate.
State and local rules can add requirements, some jurisdictions require additional notices or specific language, so confirm the current requirements for your area before you send a denial.
Store and Retain Screening Records Securely
Screening files contain Social Security numbers, dates of birth, credit reports, and background information. Treat them as sensitive data:
- Collect only what you need. Don't request information that isn't tied to a criterion in your written policy.
- Limit access. Restrict files to the people who make or review screening decisions.
- Store securely. Use a locked file or an encrypted digital folder with access controls. Avoid emailing full reports or storing them on shared drives.
If you deny an application, provide written notice as described above. Many landlords find that Full-Service Residential Property Management and Tenant Screening & Leasing services handle the entire vetting workflow, including documentation and compliance requirements, which reduces the burden of managing screening records and adverse action notices in-house.
Frequently Asked Questions
What documents should a tenant provide with a rental application?
A complete rental application should include a signed application form, government-issued photo ID, proof of current income (pay stubs or tax returns), employment verification letter, and written rental references from previous landlords. Some applicants may also provide a credit authorization form and background check consent. Collecting all required documents upfront ensures you have complete information to vet tenants effectively and reduces delays in your screening process.
How do you verify a tenant's income and employment?
Contact the applicant's employer directly by phone or email to confirm employment status, job title, and income. Request recent pay stubs (typically the last two months) and tax returns for self-employed applicants. For income verification, most landlords use a debt-to-income ratio: an applicant's monthly rent should not exceed 30% of their gross monthly income. This approach helps you assess their ability to pay rent consistently and reduces the risk of payment defaults.
What questions should landlords ask previous landlords?
Ask previous landlords about rent payment history, lease compliance, property condition at move-out, and any maintenance issues or complaints. Inquire whether the tenant gave proper notice before vacating and whether they caused damage beyond normal wear. Ask if they would rent to the applicant again. These landlord reference questions reveal patterns in tenant behavior and help you identify red flags such as late payments, noise complaints, or property damage that might indicate problems with the prospective tenant.
Can a landlord reject a rental applicant based on a background check?
Yes, but only if your decision is based on legitimate, job-related criteria applied consistently to all applicants. Under the Fair Housing Act, you cannot reject applicants based on protected characteristics such as race, color, national origin, religion, sex, disability, or familial status. You must provide an adverse action notice explaining why you denied the application. Document your screening criteria and decisions to demonstrate that you vet tenants effectively and fairly, treating all applicants the same way.